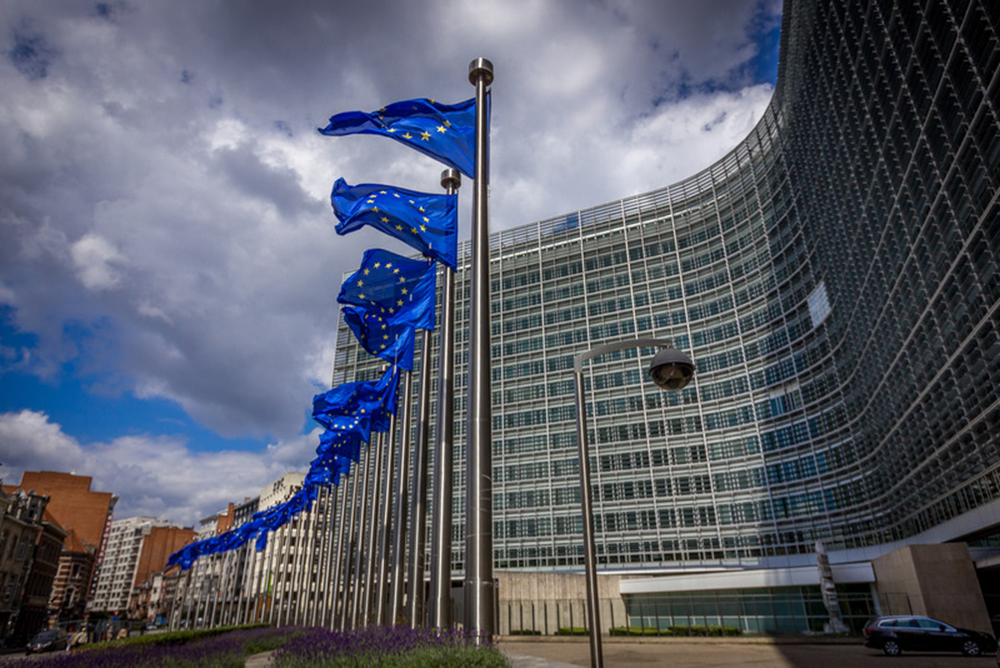
It has taken almost two years, but the European Parliament on April 16 finally endorsed the banking reform package proposed by the European Commission back in November 2016: covering key elements including the revised rules on capital requirements, and updating the framework of harmonised rules established in the wake of the financial crisis (the so-called ‘Single Rulebook’.)
The new rules will fine-tune various prudential and bank resolution aspects in order to make the banking sector more resilient to shocks while, according to the European Commission, making it “more growth-friendly and proportionate to banks’ complexity, size and business profile.”
The package implements a number of outstanding elements that are essential to make the financial system more resilient and stable, which have been finalised by global standard setters (i.e. the Basel Committee on Banking Supervision (BCBS) and the Financial Stability Board (FSB). This includes the elements of the Basel III framework already agreed at international level at the time of the Commission’s 2016 proposal. However, the more recent changes to that framework, most notably those on credit and operational risk agreed by the Basel Committee in December 2017, are not included in this banking package. The only exceptions are the revised rules on the leverage ratio and the new rules on the leverage ratio buffer.
However, some players believe the package does not go far enough. Michael Lever, Head of Prudential Regulation at the Association for Financial Markets in Europe, warns that there is more work to do on risk reduction measures.
“Much remains to be done. The European banking market continues to be segmented across national lines and the Banking Union is failing to deliver the degree of financial integration expected. Distrust amongst Member States lies at the root of this, resulting in barriers to the free flow of capital and liquidity across the EU, preventing the diversification of risk and introducing systemic fragilities,” he says.
Key measures of the new package include:
- A leverage ratio requirement for all institutions as well as a leverage ratio buffer for all global systemically important institutions;
- A net stable funding requirement;
- A new market risk framework for reporting purposes;
- A requirement for third-country institutions having significant activities in the EU to have an EU intermediate parent undertaking;
- Revised rules on capital requirements for counterparty credit risk and for exposures to central counterparties;
- A revised Pillar 2 framework;
- An updated macro-prudential toolkit;
- The exclusion of certain banks from the scope of application of the CRR and the CRD;
- A number of measures aimed at reducing the administrative burden related to reporting and disclosure requirements for small non-complex banks, as well as simplified market risk and liquidity rules for those banks;
- A new discount on capital requirements for investments in infrastructure and a more generous discount on capital requirements for exposures to SMEs;
- Targeted amendments to the credit risk framework to facilitate the disposal of non-performing loans and to reflect EU specificities;
- Targeted amendments related to the incorporation of environmental, social and governance aspects into prudential rules;
- Enhanced prudential rules in relation to anti-money laundering;
- A new total loss absorbing capacity (TLAC) requirement for global systemically important institutions;
- Enhanced Minimum Requirement for own funds and Eligible Liabilities (MREL) subordination rules for global systemically important institutions (G-SIIs) and other large banks referred to as top-tier banks;
- A new moratorium power for the resolution authority;
- Restrictions to distributions in case of MREL breaches; and
- Home-host related measures.
The legislative texts must now be formally adopted by the Council of Ministers before entering into law.
Subscribe to our newsletter